Skip to content

AI workers for African businesses, and fraud controls for the banks that serve them

Deefrent has built software in Nairobi since 2017. We now own two products: AI Digital Employees, governed AI workers for any business, and IntegWatch, financial-crime intelligence for banks, SACCOs and fintechs. This page is for investors, grant funders and partners.

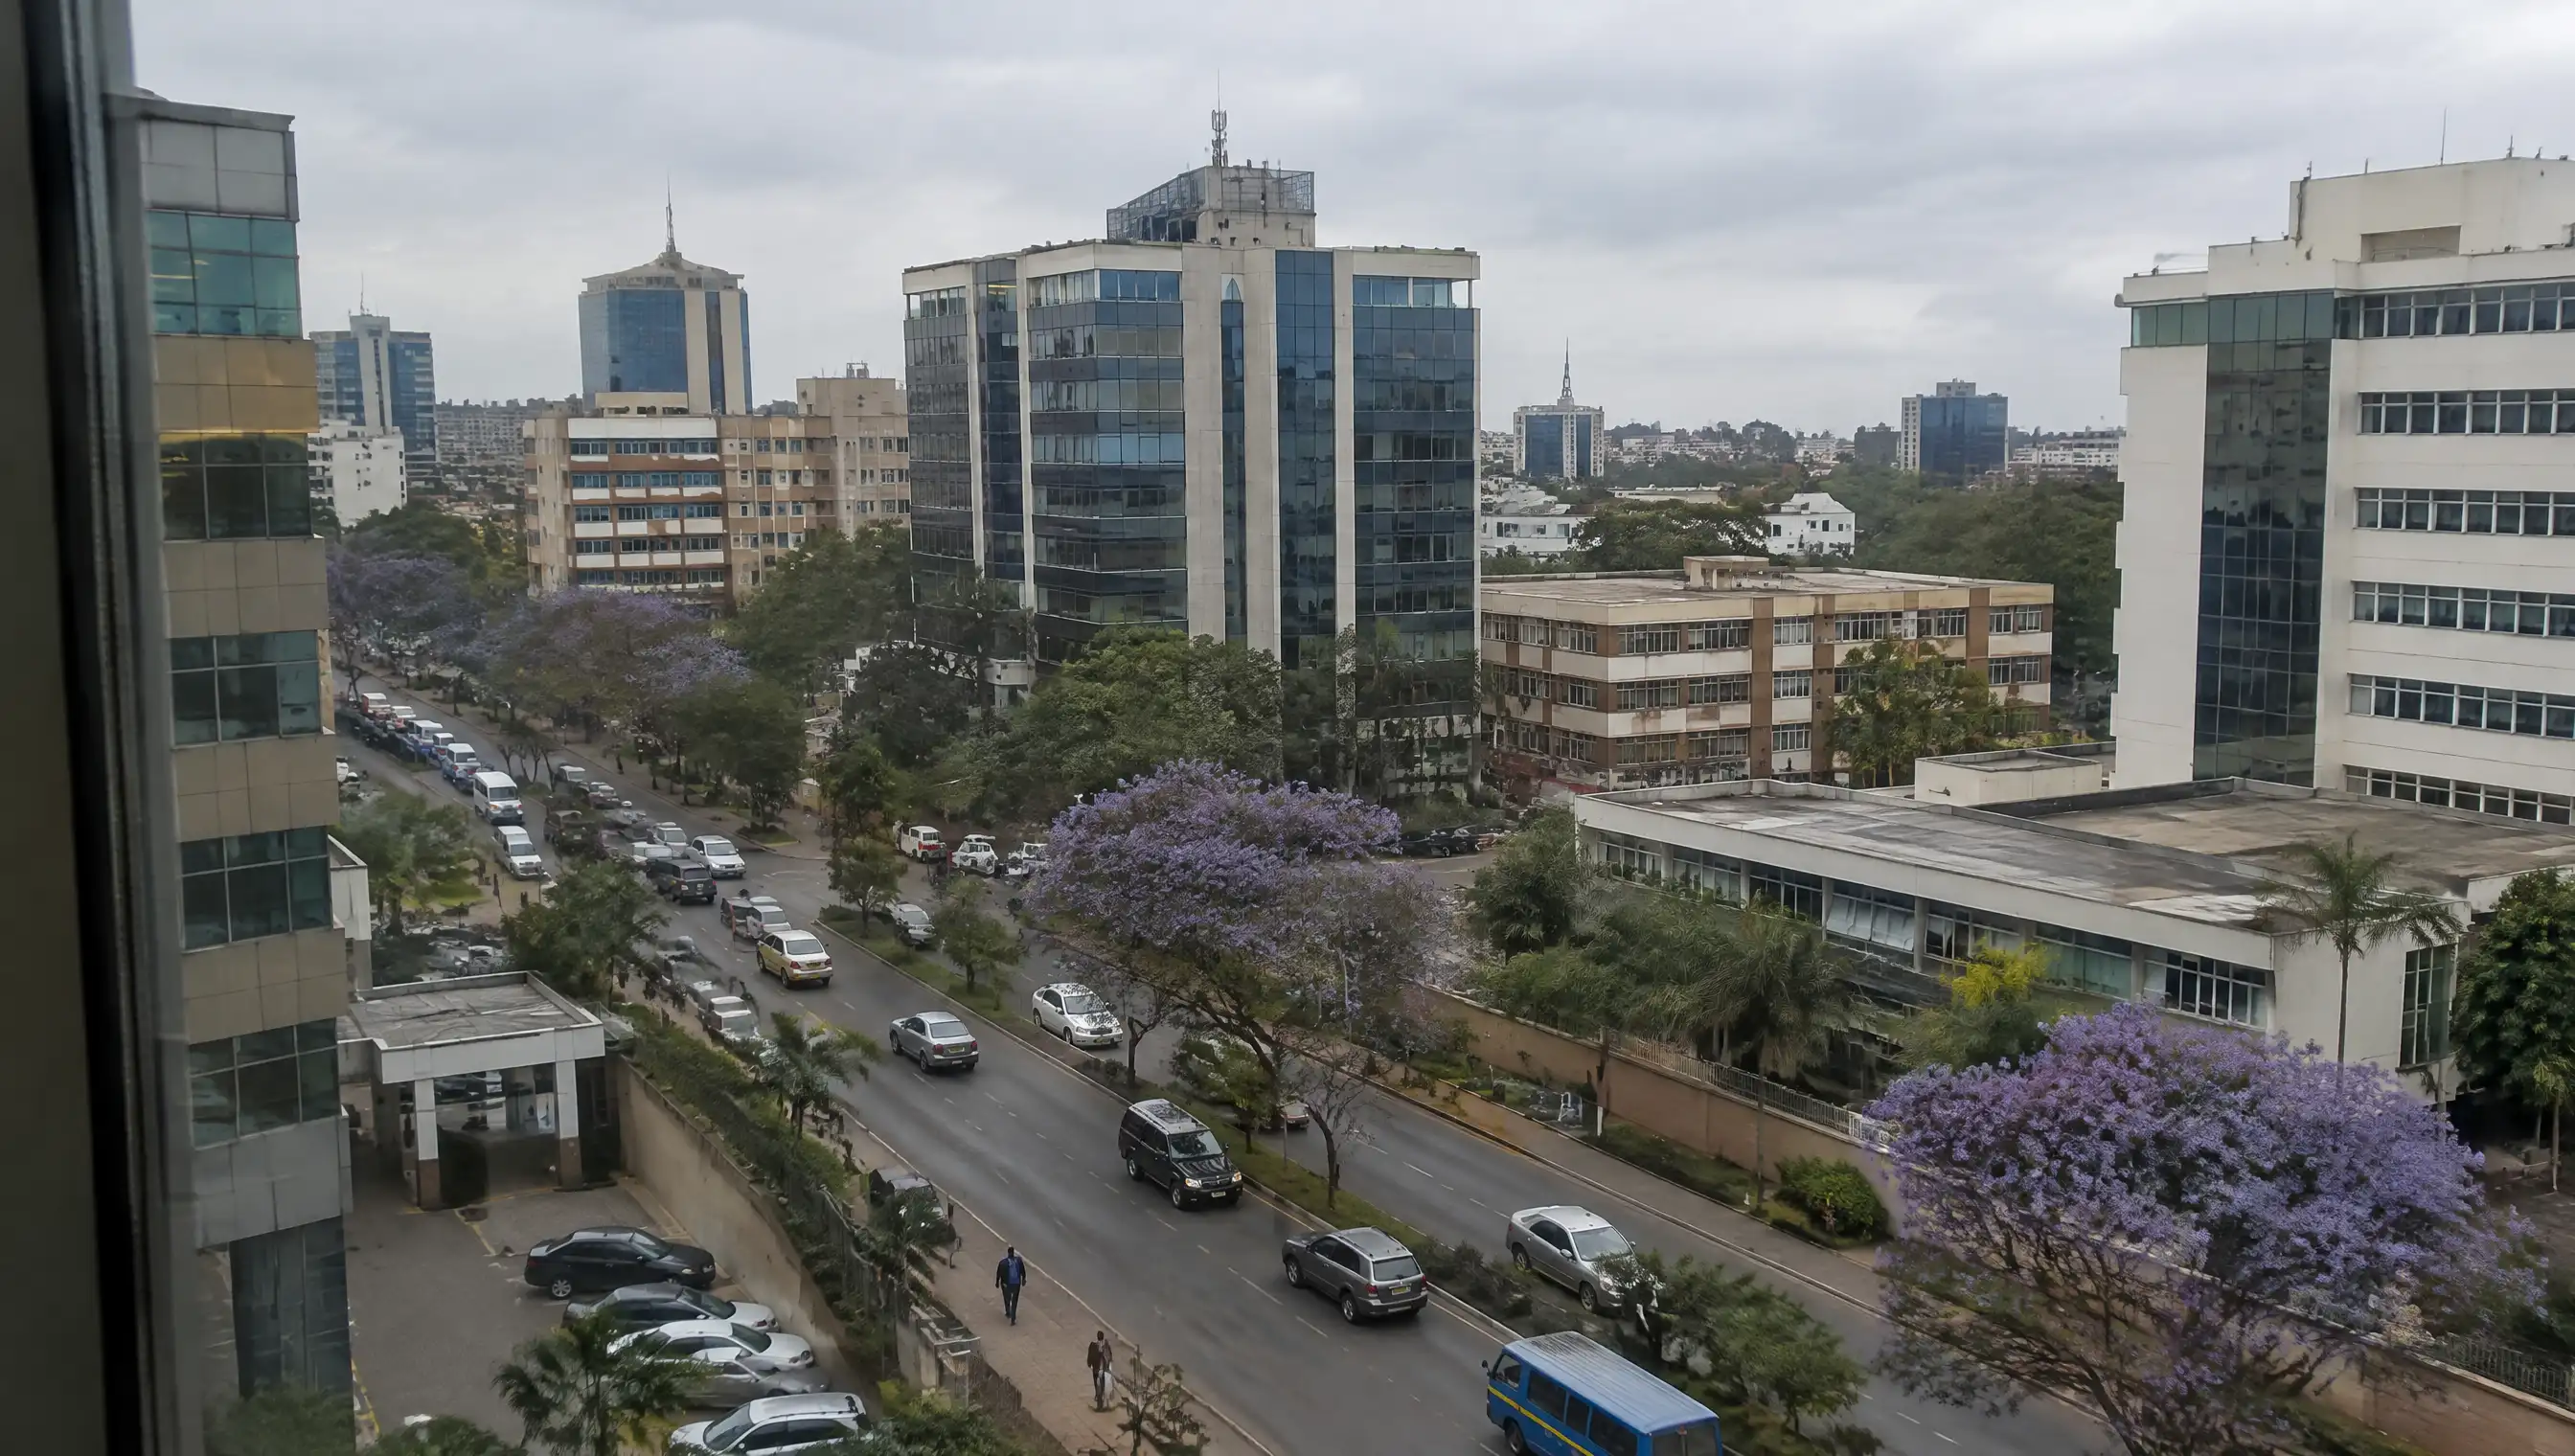
An overcast morning over Westlands, Nairobi: office blocks, traffic and jacaranda trees in bloom along the road

What we are building

Two products we own, designed to be sold by subscription and delivered by the practices that have built systems for African organisations since 2017.

How we deliver

Our practices implement both products and connect them to the systems clients already run, and they take on the integration and software projects clients bring us.

Who pays

Three kinds of customer, each reached through the same products and practices.

SMEs and mid-market firms

Businesses with 10–200 staff: distributors, clinics, SACCOs, private schools and field-service firms.

Financial institutions

Banks, MFIs, fintechs and payment providers.

The public and development sector

NGOs, development partners and government agencies.

Why now

Regulators are turning anti-money-laundering reform into technology requirements, and Kenya's tax authority now checks business expenses against electronic invoices. Each point links its public source and the date we last checked it.

  1. Kenya remains on the FATF list of jurisdictions under increased monitoring. Monitored countries have to show that their reforms work in practice, which takes monitoring, screening, reporting and audit trails, not only policies.

    SourceFATF: Jurisdictions under increased monitoring, 19 June 2026fatf-gafi.org · checked 23 September 2026

  2. The Central Bank of Kenya’s draft 2026 risk-management guidelines expect banks to run AML/CFT transaction-monitoring systems that cover customer accounts and transactions and identify unusual activity.

    SourceCentral Bank of Kenya: Draft Risk Management Guidelines, 2026centralbank.go.ke · checked 23 September 2026

  3. Since 1 January 2026, KRA checks the income and expenses in income tax returns, from the 2025 year of income, against eTIMS, withholding tax and customs records. Expenses without a valid eTIMS invoice are at risk of being disallowed.

    SourceKRA public notice: Validation of Income and Expenses in the Income Tax Returnskra.go.ke · checked 8 October 2026

  4. The Central Bank of Nigeria’s 2026 reforms set baseline requirements for automated AML/CFT systems at banks, mobile-money operators and payment service providers, and require real-time fraud monitoring for instant payments from 1 July 2026.

    SourceCentral Bank of Nigeria: 2026 reformscbn.gov.ng · checked 23 September 2026

  5. Somalia amended its AML/CFT law in 2025. The Central Bank of Somalia lists the amendment act among the regulatory guidelines for the commercial banks, money-transfer businesses, mobile-money services and microfinance institutions it supervises.

    SourceCentral Bank of Somalia: Regulatory guidelines, including the 2025 AML/CFT Amendment Actcentralbank.gov.so · checked 23 September 2026

  6. Uganda’s Financial Intelligence Authority began a regulatory impact assessment of the Anti-Money Laundering Act in 2026, a step towards reform as Uganda sustains its controls after leaving the FATF grey list.

    SourceUganda FIA: Regulatory impact assessment of the AML Act, 2026fia.go.ug · checked 23 September 2026

  7. Regional rules make compliance work reusable: the refreshed UMOA uniform AML/CFT law of February 2025 applies across eight West African states, so one compliance pack can serve a whole region.

    SourceBCEAO: AML/CFT/CPF regulations, including the 2025 uniform lawbceao.int · checked 23 September 2026
Where we work

From our office in Westlands, Nairobi, we work with organisations across East, Central, Southern and West Africa.

  • Kenya
  • Uganda
  • Tanzania
  • Somalia
  • The Gambia
  • Zambia
  • Mozambique
  • Ethiopia
  • Rwanda
  • DR Congo

Track record since 2017

Core banking, payments, identity, beneficiary and ERP systems for businesses, financial institutions, NGOs and the public sector. We describe our clients rather than name them.

Business model

Land one module, then expand. Pilots lower the barrier to a first purchase; subscriptions and implementation carry the relationship from there.

Subscriptions plus implementation

Each product is designed to be sold as a subscription. Implementation, which connects it to a client’s ERP, core banking, mobile money or bank feeds, is billed as a project by our delivery practices.

Pilots designed to convert

A pilot is scoped to one problem: one role on one channel for a digital employee, or one use case and one data feed for IntegWatch. It is measured against outcomes agreed up front and designed to convert to a subscription.

Land one module, then expand

The model starts with the most painful, auditable problem, such as payment follow-ups or sanctions screening, and adds roles, channels and modules once the first one has proved itself.

Regional compliance packs

Country and regional rule sets, reports and workflows for IntegWatch, designed to be reused across markets that share a regulatory framework.

How to engage

We share our plans in detail in the investor deck and in conversation.

Investors

Request our investor deck. We send it, answer your questions in writing and arrange a call.

Grant funders and DPI programmes

We welcome grant and digital public infrastructure partners working on financial inclusion, financial integrity and small-business productivity.

Request our investor deck

Tell us who you represent and what you invest in or fund. We send the deck, answer your questions and arrange a call. We reply within one working day.